4 655 résultats
2000réf. 91331Washington DC: United States General Accounting Office 2000. Presumed First Edition First Printing. Wraps. Very good. 30 2 pages. Footnotes. Figures. Tabular Data. Appendices. This is a "Report to Congressional Requesters". The Navy Theater Wide system is being developed to defend military and civilian assets including U.S. and allied military forces in the field against attacks by medium- and long-range ballistic missiles while they are still outside the atmosphere. The Navy is developing the system in two segments. The first segment or Block I is intended to provide an initial capability by 2010 involving the deployment of 80 interceptor missiles aboard 4 ships. For fiscal years 1997 through 1999 the Congress increased funding for the program by 150 percent--about $663 million--over the $444 million requested in the President's budgets for those years. The purpose of the increase was to enable the Navy to reduce technical risks and develop system technologies earlier than planned. The Congress expressed concern that despite the funding increases the program was viewed in 1998 by a high ranking Department of Defense official and an independent panel of experts as "high risk" because of technical challenges such as improving the system's capability to track and destroy enemy ballistic missiles. As a result Congress asked GAO to determine 1 how the additional funding provided by the Congress for the program in fiscal years 1997 through 1999 was used and 2 whether significant risks to the program remain. Within the next month we also plan to issue reports on the status of two other missile defense systems under development--the Patriot Advanced Capability-3 and National Missile Defense. GAO noted that: 1 the Navy used the $663 million in increased funding as intended to reduce technical risks and develop system technologies earlier than originally planned; 2 about 41 percent was used for system design and analysis efforts such as reducing the technical risks associated with improving the system's ability to differentiate intended targets from other objects; 3 about 20 percent of the funding was used for procuring hardware items such as rocket motors and test interceptor missiles; 4 according to program officials the additional funding also allowed the program to shift from a demonstration effort to an acquisition program in which a weapon system will be fully developed and produced; 5 although the Navy used this additional funding to reduce technical risk and develop the system sooner significant technical and schedule risks still exist; 6 technological advancement is required to differentiate the target from other objects; 7 such discrimination requires that the system's computer network can process an enormous amount of data in real time; 8 this network has not been built and its software must be integrated with the computer code that is already installed on each ship's computer system; 9 current activities include writing software examining several computer architectures for the network and building the capability to test the network; 10 technological advancement is also required in developing the capability of the interceptor missile to seek and destroy the target; 11 GAO is concerned that the program office has proposed a schedule calling for initial operational testing of the missile in 2010 even though 50 percent of the required 80 missiles would be produced and delivered by 2008 and 100 percent by 2010; 12 operational testing is designed to provide an independent evaluation of whether a system meets required performance levels prior to beginning production; 13 GAO has found that cost overruns and the deployment of substandard systems occur when the Department of Defense proceeds into production before systems are tested under operational conditions; 14 the Navy has scheduled up to 7 flight tests between July 2000 and September 2001; 15 according to testing officials test programs typically separate flight tests by about 6 months; 16 a longer interval between tests gives officials better opportunities to evaluate test results understand problems and incorporate solutions into the next test; and 17 the approved level of funding does not match the Navy program office's estimate of how much it needs to implement the program on schedule. United States General Accounting Office paperback
1999réf. 91332Washington DC: United States General Accounting Office 1999. Presumed First Edition First Printing. Wraps. Very good. 28 pages. Footnotes. This is a "Report to the Chairman Subcommittee on Defense Committee on Appropriations House of Representatives". Satellite control systems are used to ensure that satellites reach their planned orbits and perform their intended missions while in orbit. There are two types of satellite control operations-platform control and payload control. Platform controls involves monitoring the health and status and managing the operations of a satellite's physical structure sometimes called the bus. Payload controls involves monitoring the health and status and managing the operations of a satellite's mission equipment. Specific satellite control functions consist of 1 locating satellites and receiving and processing data from them 2 following satellites' motion over time and 3 transmitting signals to satellites. These three functions are called telemetry tracking and commanding and are performed by a network of ground command and control centers ground antennas and communication capabilities between the centers antennas and satellites. There are two types of satellite control networks-common and dedicated. DOD operates two common networks that provide primary or backup control for communications environmental monitoring navigation and intelligence satellites. Examples include the Defense Satellite Communications System Defense Meteorological Satellite Program and Global Positioning System. DOD also operates several dedicated networks that control missile warning communications and intelligence missions. DOD has made minimal progress in integrating and improving its satellite control capabilities in accordance with 1996 national space policy. In 1992 DOD identified a need for an integrated satellite control system to achieve standardization and interoperability across military services and individual satellite programs. In 1995 the Air Force which controls most of DOD's satellites characterized its satellite control capabilities as aging inefficient and costly to operate. The Air Force initiated an effort to standardize these capabilities and achieve full implementation in 2003-a first step toward an integrated and interoperable DOD capability. Air Force officials chose to proceed with a conceptual design over operational alternatives. However in 1997 the Air Force terminated this effort because of schedule delays resulting from software development problems and the additional amount of software that needed to be written. Air Force Space Command representatives are now recommending that the use of the Air Force's existing satellite control capabilities be extended to 2005 to provide time to acquire an improved capability. Until then the Air Force will be unable to reduce approximately $400 million it spends annually to operate maintain sustain and modernize satellite control capabilities. The Navy's satellite control capabilities are not as old inefficient or costly to operate as the Air Force's capabilities. Although the Navy upgraded its capabilities in the early 1990s another upgrade is planned because the company that provided the existing capabilities no longer provides software support services. DOD has taken limited action to foster integrated and interoperable satellite control for all government space activities since it was directed to do so by the 1996 national space policy. Prior studies recommended that a high-level interagency management group be established to oversee implementation of integrated systems across agency lines. Although DOD established a senior steering group in 1998 to address national security space management and integration issues government space agencies continue to plan for satellite control capabilities on an independent basis rather than coordinate and integrate their efforts on an interagency basis. Considering the long-standing need to replace the Air Force's aging and costly satellite control capabilities and the Navy's more recent plan to upgrade its capabilities DOD has an opportunity to revitalize its effort to achieve integrated satellite control by acquiring a standardized capability. A resumed search for such a capability is appropriate because it would also provide an opportunity to review Air Force satellite control decisions for future space-based infrared and communication satellite programs that are currently in development. Commercial off-the-shelf products that could perform core functions for controlling satellites are available and several studies have advocated the use of such products. In making a selection among alternatives DOD could reduce acquisition risk by employing best commercial practices-a key element of DOD's acquisition reform initiatives. Commercial firms place a premium on demonstrated performance before making critical decisions rather than on predicted performance as was the case with the Air Force's 1995 selection. We are recommending that the Secretary of Defense take actions to revitalize efforts to 1 integrate and improve DOD's satellite control capabilities using commercial products and practices and 2 foster integration and interoperability of satellite control among government space activities. United States General Accounting Office paperback
2000réf. 91334Washington DC: United States General Accounting Office 2000. Presumed First Edition First Printing. Wraps. Very good. 47 1 pages Footnotes. Figures. Tables. A "Report to the Chairman Subcommittee on Strategic Forces Committee on Armed Services". The increasing use of military and commercial satellite systems for national security and business purposes will have significant implications for the United States in the 21st century. The Department of Defense DOD has traditionally used satellite systems in passive roles to support military operations-for example to collect intelligence data warn of ballistic missile launches transmit voice and data communications obtain meteorological data and provide navigation signals. Now plans are being developed to expand the use of military satellite systems and develop technologies such as lasers and electronic jammers that could be used to actively conduct combat operations from space. With advances in information technology the commercial use of satellites is also expanding particularly in telecommunications. In addition single satellite systems-for example navigation environmental and imagery systems-that originally served government missions are increasingly providing capabilities to both government and commercial users. The nongovernment applications are now generating large amounts of commercial revenue. National space policy treats U.S. satellite systems as national property that organizations have the right to operate without deliberate interference. To the extent that such interference were to occur the U.S. Space Command visualizes that military forces may be called upon to provide protection just as navies protected sea commerce. The U.S. Space Command's long-range plan and the Air Force Space Command's supporting strategic master plan provide for the protection of U.S. national interests and investments in space but they do not fully conform to DOD's new space policy. The plans propose space systems only and do not provide for an assessment of the cost-effectiveness of terrestrial-land sea and air-systems as alternatives to space systems which is called for in DOD's policy. An example of such a comparative assessment would be between satellite and aircraft radar systems. In addition DOD lacks the modeling and simulation tools necessary to perform such assessments a capability that is also called for in DOD's space policy. Finally it is unclear which DOD organization has the authority and capability to perform comparative assessments between space and terrestrial systems since such assessments are outside the purview of the U.S. and Air Force Space Commands. These factors prevent DOD from being assured that the most cost-effective approaches will be considered in making decisions on the expansion of space systems. The extent to which the Air Force's 18-year program projection supports planned military space programs and desired capabilities was unverifiable. Although several of the planned space systems such as a space-based radar and a space-based laser are included in the Air Force's program projection the cost estimates in the Air Force Space Command's strategic master plan were not directly traceable to the 18-year program funding projections. They were not traceable because the data were aggregated differently and program nomenclatures differed. Air Force Space Command representatives stated that they intend to institute changes to bring about consistency between the documents. A more important matter is uncertainty about the availability of several billions of dollars in funding increases that the Air Force has projected for space system expansion. During the first 6 years of the 18-year projection fiscal years 2000-05 programmed increases are uncertain because the President and the Congress have not agreed on overall funding increases to DOD. During the last 12 years of the projection fiscal years 2006-17 the Air Force relies on planned funding increases for program modernization without identifying funding sources thus creating additional uncertainty and putting the expansion of space systems in jeopardy for affordability reasons. DOD has not given sufficient attention to providing military personnel with space education to support future military space operations. DOD's new space policy requires that information about space force structure missions capabilities and applications be incorporated into professional military education. However joint military doctrine on space operations that is necessary to implement the policy has not been issued because of disagreement among the services on the doctrine's content. Leaving the disagreement unresolved hinders common understanding for the use of space systems in military operations. In addition until the doctrine is provided DOD and military service educational institutions will lack guidance for the development of space education curricula and for determining whether existing curricula need to be modified. This report contains recommendations to the Secretary of Defense that would 1 require space plans to include analyses of terrestrial systems as alternatives 2 establish the necessary modeling and simulation tools to perform such analyses 3 identify and/or establish the DOD office to perform the analyses 4 address the delay in completing joint doctrine for space operations and 5 provide the necessary instructions to DOD and military service colleges and schools for incorporating essential space information into professional military education curricula. DOD concurred with our recommendations and provided comments. United States General Accounting Office paperback
1994réf. 91327Washington DC: United States General Accounting Office 1994. Presumed First Edition First Printing. Wraps. Very good. 31 1 pages. Footnotes. Figure. Table. This is a "Report to Congressional Requesters". The space shuttle is the only U.S. launch system capable of carrying people to and from space. It has operated for over 10 years and is likely to be used well into the next century. As the shuttle ages the National Aeronautics and Space Administration NASA will be faced with increased need to update and replace various components due to obsolescence or to enhance safety. At Congress; request GAO reviewed the shuttle program lo determine 1 the assumptions NASA has made regarding the length of time the current shuttle fleet will be in operation and 2 NASA'S processes and criteria for selecting needed safety and obsolescence upgrades. NASA has not made explicit assumptions about how long the current shuttle fleet will remain in operation. However based on its budget projections and approach to defining a new launch system the current fleet cannot be replaced for at least another 12 to 15 years. NASA'S projections of its likely budgets through fiscal year 1999 will not support simultaneous development of the space station and a new launch vehicle. NASA has a process for identifying and assessing needed upgrades. However NASA does not use life-cycle cost as a criterion for evaluating potential safety upgrades and it does not always consider alternatives when selecting an approach to implementing an improvement. Without life-cycle cost estimates NASA cannot determine whether an upgrade project is affordable within the context of the program and the agency's overall budget and out-year plans. Therefore it is possible that inappropriate program decisions on upgrades may be made. NASA managers do not have a precise basis for estimating life-cycle costs for decision purposes because of uncertainty about how Iong the current fleet will remain in operation. Since the shuttle fleet must operate for at least another 12 to 15 years it would seem logical that NASA officials could use that time period as a minimum basis for estimating life-cycle costs. NASA'S approach to funding the Safety and Obsolescence Upgrade program may increase programmatic risks. The program manager believes that funding is adequate to develop upgrade projects that have already been approved. However recent budgets have not included funds for early design studies of other potential upgrades or to cover unforeseen contingencies. Not conducting early design studies to establish the feasibility of a potential upgrade could mean that projects are not started when they are needed or projects are initiated before they are adequately defined. Also the lack of contingency funds means that if approved projects encounter unexpected problems the projects may have to be stretched out and costs may increase. This situation raises questions as to whether the decision to start two new projects in fiscal year 1995 adequately reflect budget constraints and inherent technical and cost risks. In commenting on a draft of this report NASA said that it agreed in principle with our recommendations. The agency stated however that some safety upgrades are made without a full life-cycle cost analysis because of the emphasis on safety. Safety is NASAS highest priority and relative cost is a lesser consideration. We agree that NASA must heavily weigh safety considerations in such decisions. We believe however that prudent management requires an estimate of total costs to ensure that NASA managers understand the full implications of their decisions and that the projects are affordable within the context of NASA'S total budget and future plans. United States General Accounting Office paperback
1994réf. 91341Washington DC: United States General Accounting Office 1994. Presumed First Edition First Printing. Wraps. Very good. 61 3 pages. Illustrations. Map. Tables. Some cover wear and soiling. This is a "Report to Congressional Requesters". U.S. preeminence in aeronautics is being challenged by Europe. Over the last decade European manufacturers have with the support of their governments increased their share of the global civil aircraft market to over 30 percent. In response to a Congressional request GAO have developed information on 1 the structure of the aeronautics' industries of finance Germany and the United Kingdom; 2 the support that these countries' respective governments give to aeronautical research and development R&D; and 3 the organization of the countries' respective aeronautical R&D establishments. We also obtained information on other aeronautical R&D efforts sponsored by the European Community and its member nations. The aeronautics industry is a major contributor to national security commerce and transportation. The industry is considered a technology driver that leads to spin-offs of advanced technology products that support other sectors of the national economy. The aeronautics industry comprises three major sectors-airframe engine and equipment. This report focuses on the airframe and engine sectors. The airframe sector usually includes final assembly of the aircraft. En 1992 manufacturers in France Germany and the United Kingdom sold aeronautics products valued at about $52 billion. Civil and military aeronautics products contributed roughly equally to that amount except for Germany where civil products accounted for about 61 percent of sales. The countries exported aerospace products worth about $31 billion roughly a $lO-billion increase over 1989. Aeronautics products for France and the United Kingdom made up over 89 percent of their countries' aerospace export totals. Although 1992 data were not available for Germany 1991 statistics show the total to be in excess of 90 percent. In the three countries about 310000 people worked in aeronautics-related activities. As a point of reference the aeronautics industry in the United States had sales of about $74 billion exported about $44 billion and employed about 611000 people in 1992. United States General Accounting Office paperback
1991réf. 91339Washington DC: United States General Accounting Office 1991. Presumed First Edition First Printing. Wraps. Very good. 41 3 pages. Footnotes. Illustrations. Tabular data. This is a "Report to the Chairman Subcommittee on Science Technology and Space Committee on Commerce Science and Transportation U.S. Senate". Pursuant to a congressional request GAO reviewed the National Aeronautics and Space Administration's NASA testing activities focusing on: 1 the adequacy of the NASA testing policies and practices; 2 NASA oversight of contractor testing; and 3 the adequacy of resources available for testing. In April 1990 NASA deployed its $1.5 billion Hubble Space Telescope to an orbit 380 miles above the earth. Soon after the agency discovered that the telescope's primary mirror was manufactured in the wrong shape severely degrading its scientific capabilities. The flaw was not detected before the telescope was launched because the mirror was not adequately tested. The Chairman Subcommittee on Science Technology and Space Senate Committee on Commerce Science and Transportation asked GAO to review NASA'S testing activities. Specifically GAO'S objectives were to assess the adequacy of testing policies and practices and the agency's oversight of contractor testing and to determine whether sufficient resources existed for testing. Because space missions are inherently risky systems cannot be easily repaired while in orbit and failures are widely publicized it is especially important that the systems' performance be thoroughly tested before launch. These complex systems are usually acquired in very limited quantities and test programs are specifically tailored for each project. According to a NASA team appointed to investigate the Hubble failure mirror tests were inadequately planned and poorly analyzed. The team further noted that NASA did not provide adequate oversight of the contractor's test program. Testing has varied from project to project. The success of many of NASA'S recent space projects indicates that in many cases testing was adequate. Tests were not effective however in detecting the Hubble mirror flaw. In other cases launch schedules have been adversely affected because tests did not identify problems soon enough. Testing practices vary because NASA has no uniform policies governing testing. Existing guidance is fragmented not well defined and varies from one NASA field center to another. In some cases hardware designed for the same mission may be tested to different standards. All centers have oversight controls to help ensure that contractors properly plan and conduct tests and report the results. Controls at some centers however could be further strengthened. Also according to a recent National Academy of Public Administration study NASA needs to retain more of its research and development work in-house to give civil service personnel the experience necessary to adequately oversee agency contractors. No standard exists for determining the amount of resources that should be devoted to testing but according to NASA officials resources are normally sufficient to conduct essential tests. However project managers must sometimes make cost-risk tradeoffs when defining the scope and extent of testing programs. Further some in-house test facilities and equipment need upgrading. United States General Accounting Office paperback
2000réf. 91333Washington DC: United States General Accounting Office 2000. Presumed First Edition First Printing. Wraps. Very good. 20 4 pages. Footnote. Figure. Table. This is a "Report to the Chairman Committee on Commerce Science and Transportation U.S. Senate". The National Aeronautics and Space Administration's NASA space shuttle program is at a critical juncture as three key factors converge: its workforce has declined significantly since 1995 its flight rate will have to double over that of recent years to support assembly of the International Space Station and costly safety upgrades are being planned to enhance the space shuttle's safe operation until at least 2012. Several internal NASA studies have shown that the shuttle program's workforce has been affected negatively by the downsizing much of which occurred after 1995. Since 1995 the shuttle workforce has decreased by more than one-third to about 1800 full-time equivalent employees. The shuttle program has identified many key areas that are not sufficiently staffed by qualified workers and the remaining workforce shows signs of overwork and fatigue. For example indicators on forfeited leave absences from training courses and stress-related employee assistance visits are all on the rise. Moreover the program's demographic shape has changed. For example throughout the Office of Space Flight which includes the shuttle program there are more than twice as many workers over 60 years old than under 30 years old. This jeopardizes the program's ability to hand off leadership roles to the next generation and achieve a higher flight rate to support assembly of the International Space Station. In addition according to NASA it poses significant shuttle program flight safety risks. NASA has recognized the need to revitalize its workforce. For example in December 1999 it terminated shuttle program downsizing plans and initiated efforts to begin hiring new staff. In addition NASA and the Office of Management and Budget have begun an overall workforce review to examine personnel needs barriers to achieving proper staffing levels and skill mixes and potential reforms to help address the agency's long-term requirements. NASA human resource officials told us that they are now using a draft checklist we recently published as a guide in ongoing workforce planning and in discussions with the Office of Management and Budget. The checklist includes a five-part framework: strategic planning organizational alignment leadership talent and performance culture. The guide should help NASA to more clearly establish a linkage between human capital programs and the agency's mission goals and strategies. In addition the Government Performance and Results Act requires a performance plan that describes how an agency's goals and objectives are to be achieved. These plans are to include a description of the 1 operational processes skills and technology and 2 human capital information and other resources required to meet goals and objectives. In reviewing NASA's fiscal year 2000 annual performance plan we found that the plan does not adequately describe how the agency's strategies and human capital resources will help it achieve performance goals. NASA's fiscal year 2001 plan however addresses at least some human capital issues in that it includes an objective to improve workforce health monitoring. In addition in June 2000 the President directed the heads of all executive branch federal agencies to integrate human resource management into planning budgeting and mission evaluation processes. The directive requires each agency to include specific human resource management goals and objectives in its strategic and annual performance plans beginning October 1 2000. The President's June 2000 directive provides further emphasis on the need to integrate human capital requirements with the strategic planning process continued management emphasis will be critical to the success of NASA's human capital planning. In addition NASA will need to take steps to ensure it has the right people to manage the shuttle program Because the President has now directed NASA and all other executive branch agencies to include human capital goals and objectives in their strategic and annual performance plans GAO is not making recommendations in this report. We will monitor NASA's progress in establishing and achieving its human capital goals as part of our annual performance plan assessments. United States General Accounting Office paperback
2017réf. Adhya-9781259921285MC GRAW HILL 2017. HB. New. MC GRAW HILL hardcover
réf. 0256094187.Gpaperback. Good. Access codes and supplements are not guaranteed with used items. May be an ex-library book. paperback
1999réf. 91264Washington DC: United States General Accounting Office 1999. Presumed First Edition First Printing. Wraps. Very good. 34 pages. Report to Congressional Requesters. The purpose of the $1.3 billion X-33 Program cosponsored by the NASA and the Lockheed Martin Corporation is to develop and demonstrate advanced technologies and techniques needed for future reusable launch vehicles RLV including lightweight internal fuel tanks advanced rocket engines a durable heat shield and rapid-turnaround low-cost operations. The X-33 vehicle will be a half-scale model of Lockheed Martin's planned single-stage-to-orbit SSTO Venture Star RLV an operational vehicle that will be based on and developed after the X-33. Lockheed Martin and NASA will base the decision to proceed with developing the Venture Star in part on the results of the X-33 Program. NASA would potentially be one of Lockheed Martin's primary customers for the cargo-only flights and is the only anticipated customer for passenger flights. The passenger flights would carry crewmembers to and from the International Space Station. NASA and Lockheed Martin are conducting the X-33 Program under a cooperative agreement a financial instrument with which a government entity and one or more public or private organizations jointly fund and implement an activity to achieve common objectives. Such a partnership was encouraged by the National Space Transportation Policy of 1994 as a means of 1 establishing NASA as the lead agency for technology development and demonstration of reusable space transportation systems and 2 positioning the government and the private sector to make decisions on the development of an operational reusable launch system. NASA and Lockheed Martin X-33 program managers anticipate that the program will achieve technical requirements such as demonstrating the feasibility of building large liquid hydrogen fuel tanks made of graphite composite material. However the program will not meet some original cost schedule and performance objectives. Problems encountered by Lockheed Martin while working toward the X-33 Program's technical requirements have caused cost increases delay of the test vehicle's first flight and revision of some performance objectives. The technical problems occurred during development and fabrication of the X-33 vehicle's internal fuel tanks rocket engines and thermal protection system the three key advanced technologies the program seeks to demonstrate. Resolving these technical problems caused Lockheed Martin's estimated contribution to grow $75 million above the original estimate of $211.6 million to $286.6 million. However part of the increase will be borne by the government. Procurement regulations allow companies to recover allowable independent research and development costs by including them as overhead in the pricing for other government contracts. Thus Lockheed Martin's and its partners' shares may actually be lower. In addition estimated government costs for NASA civil service personnel working on the program not included in NASA's X-33 program budget also increased. Together these estimated costs increased from $216.9 million to $274.3 million as of March 1999. As a result we believe a more accurate representation of the estimated government's share of the X-33 Program is $1.23 billion while industry's estimated share is $125.4 million. Several issues will need to be evaluated before NASA decides to use Venture Star RLVs to support the International Space Station. First the results of the X-33 Program must provide sufficient information for NASA to determine that the risks have been sufficiently reduced and that continuation of activities leading to the agency's use of Venture Star as a customer is warranted. Second even though Venture Star RLVs are intended to be commercially owned and operated government financial incentives will likely be needed to initiate such a venture. Third NASA would have to pay for either two crew modules or modifications to Venture Star vehicles if the crew return vehicle being developed for the International Space Station is chosen as a means for Venture Star to carry people. Fourth because the Venture Star RLV would not carry as much cargo as the space shuttle additional flights would be needed. The more frequent docking activities may reduce the amount of stable time available for some science operations. United States General Accounting Office paperback
1996réf. 91266Washington DC: United States General Accounting Office 1996. Presumed First Edition First Printing. Wraps. Very good. 33 3 pages. The National Aeronautics and Space Administration NASA is facing the difficult task of fulfilling its mission with significantly fewer dollars. NASA's present strategy for absorbing its most recent funding reductions through fiscal year 2000 focuses on cutting infrastructure. If NASA fails to find and implement sufficient infrastructure cost-reduction opportunities meeting its budget targets through fiscal year 2000 will require program adjustments-stretching out reducing the scope or terminating efforts and/or postponing new initiatives. GAO reviewed the status of NASA's efforts to achieve reductions and efficiencies in its infrastructure principally facilities and the challenges it faces. In the early 1990s NASA was planning an infrastructure to support a projected annual budget of more than $20 billion and a civil service workforce of about 25000 by the turn of the century. However NASA has been directed by the Administration to reduce its future years' budget levels. In FY 1994 budget request NASA's total funding for fiscal years 1994 through 2000 was reduced by 18 percent or $22 billion. In the FY 1995 budget request total funding was reduced again by an additional 13 percent. To absorb these reductions NASA focused on adjusting programs. The Space Station program was restructured and given an annual budget ceiling of $2.1 billion. The scope of the Earth Observing System program was reduced. Funding was terminated for the Space Exploration Initiative the National Launch System and the National Aerospace Plane. The Comet Rendezvous and Asteroid Flyby project was canceled. NASA's current facility closure and consolidation plans will not fully achieve the agency's goal of decreasing the current replacement value of its facilities by about 25 percent about $4 billion in 1994 dollars by the end of fiscal year 2000. More importantly these plans will not result in substantial cost reductions by that date. Also although NASA is about half way to its goal of lowering the number of its full-time equivalent employees to 17500 by fiscal year 2000 it faces major uncertainties in achieving additional workforce reductions. NASA has also had problems in evaluating some cost-reduction opportunities; environmental cleanup costs could affect future facility disposition efforts; and its efforts to share facilities with DOD have progressed slowly. NASA faces barriers to accomplishing additional consolidations and closures that to date it has not been able to overcome on its own. Closing facilities relocating activities and consolidating operations in fewer locations with fewer employees have been slowed by parochial concerns about the effects of such actions on missions personnel and local communities. These concerns have been exacerbated by perceptions of the lack of fairness and impartiality in the decision-making process. In the face of these concerns NASA must still reduce its infrastructure further. Ultimately if further progress in identifying and implementing infrastructure reductions is limited a process that uses an external independent group similar to the Defense Base Closure and Realignment Commission may be needed. To help determine the need for an independent group to facilitate closures and consolidations of NASA facilities Congress may wish to consider requiring NASA to submit a plan outlining how it intends to met its reduction goals. United States General Accounting Office paperback
1995réf. 91265Washington DC: United States General Accounting Office 1995. Presumed First Edition First Printing. Wraps. Very good. 31 1 pages. Briefing Report to the Ranking Minority Member Subcommittee on Space and Aeronautics Committee on Science House of Representatives. In April 1994 the National Aeronautics and Space Administration NASA estimated that it would cost about $475 million for a Titan IV-Centaur launch of its Cassini spacecraft. Concerned about the cost as the Chairman of the former Subcommittee on Space House Committee on Science Space and Technology you requested that we provide information about the current estimated cost for the Cassini launch and determine the extent to which cost saving opportunities exist. On April 11 1995 we briefed your staff on the results of our work. This report contains the information presented at that briefing. NASA plans to launch its Cassini spacecraft to Saturn in October 1997. Following a voyage of more than 6 years the spacecraft will orbit Saturn for 4 years. Cassini will provide intensive long-term observations of Saturn's atmosphere rings magnetic fields and moons. Cassini's probe will be used to analyze the atmosphere of Saturn's largest moon Titan. Cassini a joint U.S.-European mission was originally paired with a project to explore comets and asteroids the Comet Rendezvous Asteroid Flyby CRAF. Cassini was first funded by Congress in fiscal year 1990. Since then CRAF was canceled and Cassini's original scientific capabilities have been reduced and its launch schedule extended. NASA is responsible for the overall success of the Cassini mission including integrating the spacecraft with the launch vehicle and approving the final launch. Under an agreement with NASA the Air Force will provide a Titan IV expendable launch vehicle with a Centaur upper stage and launch service from Cape Canaveral Air Force Station in Florida. NASA's most recent estimate for the Titan IV-Centaur launch of its Cassini spacecraft is about $452 million approximately $23 million less than its $475-million estimate in April 1994. The decrease occurred principally because NASA reduced its earlier estimate of mission integration costs. The $452-million estimate includes about $253 million paid to the Air Force for a Titan IV-Centaur launch vehicle and launch services. The remaining Cassini launch costs are NASA funding to pay for potential future cost increases mission integration prior-year studies support by two NASA field centers and miscellaneous costs. The Air Force estimates that its cost for launch vehicle and services is about $98 million more than the $253 million NASA will pay. Air Force officials believe there are benefits to providing a launch vehicle for Cassini. For example the Air Force will avoid an estimated $11.5 million to $13.8 million in storage charges and will reduce mission reliability risk due to the aging of components. Reductions in the cost of the Cassini launch may be possible because NASA recently completed its negotiation of the mission integration contract for $15 million less than estimated. However cost savings in other areas of the Cassini launch are unlikely and some of NASA's costs could increase. Also NASA missed a potential cost-saving opportunity because its agreement with the Air Force does not require the Air Force to refund NASA payments in excess of cost. Consequently the Air Force is not required to refund to NASA fees that the Air Force does not pay to the Titan IV contractor. These fees include $2 million in award fees and a $9-million incentive fee. In addition NASA's mission integration contract does not fully comply with the agency's revised policy for cost-plus-award-fee contracts which was implemented to encourage contractors to deliver quality products at reasonable costs. United States General Accounting Office paperback
1997réf. 91261Washington DC: United States General Accounting Office 1997. Presumed First Edition First Printing. Wraps. Very good. 40 pages. Report to Congressional Requesters. This report discusses 1 the Department of Defense's DOD and the National Aeronautics and Space Administration's NASA requirements for surveillance of space objects and 2 DOD's space surveillance capabilities to support these requirements. This report contains recommendations to the Secretary of Defense and the Administrator of NASA. We are sending copies of this report to the Secretaries of Defense the Air Force the Navy and the Army; the Administrator of NASA; the Directors of the Office of Management and Budget the Office of Science and Technology Policy and the Central Intelligence; and other interested congressional committees. During the past 40 years the number of manmade space objects orbiting the earth-active and inactive satellites and debris generated from launch vehicle and satellite breakups-has increased dramatically. Knowing what objects are in space and their locations are important because of the 1 implications of foreign satellite threats to U.S. national security and 2 hazards that such objects create for multibillion dollar space programs especially large ones such as the International Space Station. DOD's existing space surveillance network is not capable of providing the information NASA needs to adequately predict collisions between space objects orbiting the earth and multibillion dollar space programs such as the space station. Moreover the existing network cannot satisfy DOD's emerging space surveillance requirements which are currently under review. DOD's plans to 1 modernize an existing surveillance network radar system and 2 develop three new ballistic missile warning systems which could contribute to performing the surveillance function do not adequately consider DOD's or NASA's surveillance requirements. These four systems are separately managed by the Navy the Air Force and the Army. An opportunity exists to consider these systems' potential capabilities to enhance the surveillance network to better satisfy requirements and achieve greater benefits from planned investment in space sensor technology. Despite NASA's dependency on DOD to provide space object information the 1996 National Space Policy makes no provision for an interagency mechanism-either organizational or funding-to ensure that DOD's surveillance capabilities satisfy NASA's requirements. Overall there is no authoritative direction formal agreement or clear plan on how DOD and NASA could consolidate their space surveillance requirements for a common capability. A coordinated interagency plan that considers all existing and planned space surveillance capabilities could be beneficial in making cost-effective decisions to satisfy a consolidated set of national security and civil space surveillance requirements. Unless DOD and NASA can agree on such a plan an opportunity may be missed to simultaneously 1 achieve efficiencies; 2 better ensure the safety of the planned multibillion dollar space station; and 3 help satisfy national security needs including the U.S. forces' future needs for space asset information. United States General Accounting Office paperback
1998réf. 91268Washington DC: United States General Accounting Office 1998. Presumed First Edition First Printing. Wraps. Good. 46 pages. Front cover corner creased. Report to the Chairman and the Ranking Minority Member Subcommittee on Science Technology and Space Committee on Commerce Science and Transportation U.S. Senate. The National Aeronautics and Space Administration NASA and the Department of Defense DOD operate several types of aerospace test facilities including wind tunnels and rocket engine test stands. The NASA and the DOD operate several types of aerospace test facilities including wind tunnels and rocket engine test stands. Congress has been appropriating less money for aerospace programs. In response to declining budgets and reductions in personnel NASA and DOD agreed in 1995 to perform essential aerospace testing on a more cooperative basis. The agencies recommended in April 1996 that they establish joint working groups to assess and make recommendations on investments and other issues. GAO is providing the results of our review of NASA's and DOD's cooperation since May 1996 to develop a national perspective on aerospace test facilities. To assess the progress GAO determined 1 the extent to which NASA/DOD working groups on major test facilities have been operating on a regular basis 2 NASA's and DOD's actions in response to a future need to test an engine for new Air Force rockets 3 whether NASA and DOD prepared a congressionally required joint plan on rocket propulsion test facilities and 4 whether NASA and DOD are implementing a DOD assessment team's recommendation in 1997 to jointly manage with NASA certain aeronautical test facilities. This report includes a matter for congressional consideration. The GAO found that the promise of closer NASA/DOD cooperation and the development of a national perspective on aerospace test facilities remains largely unfulfilled because NASA and DOD 1 have not yet convened most test facility alliances 2 compete with each other to test engines for new rockets and 3 did not prepare a congressionally required joint plan on rocket propulsion test facilities. Although NASA and DOD have agreed to go beyond cooperative alliances in aeronautics and jointly manage their aeronautical test facilities they have not yet reached agreement on key aspects of a management organization. NASA and DOD took 20 months May 1996 through Dec. 1997 to negotiate and sign agreements formally establishing the six test facility-related cooperative alliances. During that time only the space environmental simulation alliance met regularly and conducted business. The already established rocket propulsion alliance met only once during this period despite a desire by some members to meet regularly. NASA and DOD officials did not regularly convene the other four alliances in the absence of approved charters. Despite the formation of the rocket propulsion alliance NASA and DOD compete against each other to test engines for new rocket programs. A principal arena of competition is the next phase of the Air Force's Evolved Expendable Launch Vehicle EELV program. In particular the Air Force has spent millions of dollars to upgrade a test stand on the assumption that it not NASA would test EELV engines. DOD did not prepare a legislatively mandated joint plan with NASA to coordinate rocket propulsion test facilities. United States General Accounting Office paperback
1819réf. 91335Washington DC: United States General Accounting Office August 18 1994. Presumed First Edition First Printing. Wraps. Very good. 46 pages. A "Report to the Chairman Committee on Government Operations House of Representatives". Federal procurement Contract administration Aerospace contracts Contract modifications Contract costs Contractor performance Work measurement standards Small business contractors Human resources training Contractor responsibility. United States General Accounting Office paperback
1998réf. abc4199Institute of Chartered Accountants of Scotland 1998 Institute of Chartered Accountants of Scotland. 1998 paperback 73 pages a slight bend to the book but this is A BRAND NEW BOOK UNUSED. Full refund if not satisfied. 24 hour despatch via Tracked. If not pictured in this listing a scan of the actual book is available on request. Soft cover. As New. Institute of Chartered Accountants of Scotland paperback
1999réf. 91247Washington DC: United States General Accounting Office 1999. Presumed First Edition First Printing. Wraps. Very good. 38 pages. Illustration. Tabular Data. Footnotes. This is a "Report to Congressional Requesters". When completed around 2004 the goal of the International Space Station ISS is to provide the United States and its international partners with an Earth orbiting facility that supports human habitation and scientific research in a microgravity environment. Because of Russia's ongoing problems in funding its share of the space station's construction costs the National Aeronautics and Space Administration NASA is concerned that Russia may also not be able to fulfill its commitments to fund ISS operations costs. NASA estimated that the annual cost to operate the completed space station will average $1.3 billion or $13 billion over a 10-year mission life. NASA anticipates sharing these costs with its international partners and it hopes to further reduce funding requirements through sharing with commercial users or through more efficient commercial operations. As requested by you and the late Representative George E. Brown Jr. we reviewed NASA's estimate for the cost to operate the space station after assembly is completed. Specifically we were asked to determine 1 if any space station-related costs are not included in NASA's estimate; 2 the level of uncertainty in the cost estimate for operations especially with regard to the potential impact of changes in Russian participation; and 3 how NASA funding requirements will be reduced by sharing costs with international partners or through commercial use and operations. NASA's $1.3 billion estimate does not include all funding requirements related to space station operations. NASA does not prepare budget estimates on a full-cost basis because it has not completed implementation of its full cost accounting system. Additional items that will have to be funded in the future within the space station budget include costs for upgrading obsolete systems and operating an alternative propulsion module. NASA has not developed detailed estimates for potential upgrades to combat component obsolescence and improve performance but space station officials believe that a robust enhancement program could cost $100 million or more per year. NASA has not estimated the cost of operating an alternative propulsion module being procured to provide reboost if Russia is unable to provide that function. Items that we determined to be space station-related that are funded in other NASA budget lines include space shuttle flights civil service personnel principal investigators and space communications; these are estimated to cost a total of $2.5 billion in fiscal year 2004. When NASA implements full cost accounting in 2001 some costs currently in other NASA budget lines will be included in the space station budget. In commenting on our draft report NASA stated that shuttle flights should be allocated to the overall cost of operating the space station using a marginal cost of $84 million per flight rather than an average cost of $435 million. We believe the average cost per flight more accurately represents NASA resources related to operating the space station. There is a high degree of uncertainty in NASA's estimate for the cost to operate the space station from 2005 to 2014. NASA's original estimate of $13 billion for operating the space station was developed to aid in evaluating life-cycle costs of redesign options rather than to accurately forecast budget needs. This estimate did not consider end-of-mission costs for either extending the life of the space station beyond 10 years or decommissioning it. The estimate was also developed for an earlier space station configuration that has since been modified. NASA does not prepare detailed budget estimates for the space station and other programs beyond fiscal year 2004 the last year of its current 5-year budget-planning period. NASA recently began an effort to review its operations cost estimate and develop a long-range funding profile that would better reflect annual requirements over the 10-year operations period. Adding to the uncertainty of future costs the full impact on operations if Russia is unable to fulfill its obligations is not known at this time. NASA would incur costs to operate an alternative propulsion module but does not yet know whether there will be a shortfall in Russian logistics flights or how such a shortfall would be spread among the shuttle and international partner resupply vehicles. United States General Accounting Office paperback
1998réf. 91246Washington DC: United States General Accounting Office 1998. Presumed First Edition First Printing. Wraps. Very good. 23 1 pages. Footnotes. Illustrations. Tabular data. This is a "Report to Congressional Requesters". This report responds to a Congressional request that the GAO review the National Missile Defense NMD program funding requirements and schedule and technical risks. Specifically you asked us to determine 1 why the Department of Defense DOD significantly increased the program's near-term funding in its May 1997 Quadrennial Defense Review 2 how funding increases authorized and appropriated by Congress for the program in fiscal years 1996 through 1998 have been used or are planned to be used and 3 DOD's planned level of future funding for the NMD program and planned uses for those funds. You also asked for an assessment of the program's current schedule and technical risks. We provided an initial assessment of the schedule and technical risks in our December 12 1997 report to you. This report updates that assessment. The primary mission of NMD is to defend the United States against an intercontinental ballistic missile attack consisting of several missiles launched from a rogue nation. It would also have some capability against an accidental launch from nuclear powers such as Russia or China. The United States has been developing technologies for use in an NMD system for a number of years. In April 1996 DOD changed the purpose of the NMD program from a technology readiness program to a deployment readiness program and designated NMD as a major defense acquisition program. Under the technology readiness program the Ballistic Missile Defense Organization BMDO developed and matured technologies for possible use in an NMD system. Under the current deployment readiness program BMDO plans to integrate the technologies into a system that can be made operational. The deployment readiness program is commonly known as the "33" program. The goal of the NMD 33 program is to develop and demonstrate by fiscal year 2000 an initial limited capability that could be deployed by fiscal year 2003. The deployment decision is to be based on ongoing assessments of the threat and will not be made until fiscal year 2000 at the earliest. If DOD concludes at that time that the threat does not warrant deployment by fiscal year 2003 development will continue. While BMDO is still determining the specific design of the initial NMD system its features will include 1 space- and ground-based sensors to provide early warning of attacking missiles; 2 ground-based radars to identify and track the threatening warheads; 3 ground-based interceptors to collide with and destroy incoming warheads; and 4 a battle management command control and communications system. United States General Accounting Office paperback
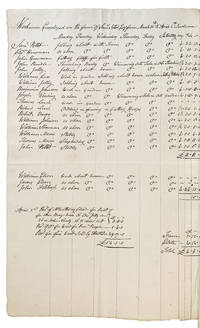
1812réf. BL4695Ecton Borough of Wellingborough Northamptonshire England:: 1812. 1812. Folio. 5 folded sheets approx. 19 x 15 1/2 inches. Condition: Excellent. Manuscript record of the worker salaries paid to operate the March 30-May 2 1812 farm at the estate of Samuel Isted Ecton. Each sheet being a record of five weeks labor lists the workers names the days they worked their duties on the farm and the costs of the laborers as well as totals. Additional entries are made for "work about the home" handymen and another provision annotates the income received from rent sale of wood etc. The details are what is of particular interest including a list of the number of farm animals and their types "Stock of Beasts" 9 heifers 7 cows 1 bull; Sheep: 5 rams home bred 1 ewe 1 lamb 4 lambhogs 2 south down rams 125 ewes 142 lambs 30 Welch sheep. Three men are named for "work about the home" William and James Elson John Fitsburgh. There are 17 workers named for working the farm: Samuel Pettit Charles Hensman John Hensman John Randle John Jolley William Cox William Jolley Benjamin Johnson Joseph Wooding Thomas Leach Richard Leach Robert Burges William Johnson William Sharman William Morris Thomas Morris and John Pettit. Their labors are listed as: jobbing about with team cutting chaff for cloth threshing barley & winnowing oak take in oak threshing jobbing about the home work in gardens ditching & fencing & cutting hedges stables sheep herding. One entry refers to payment rec'd for "wood for Poor People" and another entry states "rec'd for fine wood sold by auction." Another separate column details added expenses listed by days of the week: Paid the clerk his Church dues paid for looking after fowls paid . . . for advertising wood sale and selling wood paid for trussing allowance payment for cutting and quarter of chaff paid expense with team fetching 2 loads of coal & 2 loads of lime. With each successive week one can see how the daily operations are handled and paid for income earned and all the names of every worker. ALSO: verso of April 6-11 leaf adds entries: Rec'd of Mr.W James Mowkim! payment for a fat cow lambhog lamb ewe rams Welch sheep pig calf cow etc. Samuel Isted Esq of Ecton baptized on May 17th 1750 wedded in 1795 to Barbara eldest daughter of Thomas Percy Lord Bishop of Dromore. Samuel died August 12 1827 buried at Ecton. They had one daughter who died in infancy and a son Ambrose Isted d.1800. Note: Benjamin Franklin's father Josiah Franklin was a tallow chandler a soap-maker and a candle-maker. He was born at Ecton Northamptonshire England on December 23 1657 the son of Thomas Franklin a blacksmith-farmer and Jane White. Benjamin Franklin himself was known to visit Ecton. Thus one of the founding fathers of the United States had roots in Ecton. Franklin himself wrote "The notes one of my uncles who had the same kind of curiosity in collecting family anecdotes once put into my hands furnished me with several particulars relating to our ancestors. From these notes I learned that the family had lived in the same village Ecton in Northamptonshire for three hundred years . . . is eldest son Thomas lived in the house at Ecton and left it with the land to his only child a daughter who with her husband one Fisher of Wellingborough sold it to Mr. Isted now lord of the manor there." – Franklin's autobiography. 1812. hardcover
réf. 133013625X.Gpaperback. Good. Access codes and supplements are not guaranteed with used items. May be an ex-library book. paperback
réf. 1330298136.Gpaperback. Good. Access codes and supplements are not guaranteed with used items. May be an ex-library book. paperback
1997réf. UNDER528MA4667Palgrave Macmillan 1997-02-07. Hardcover. Like New. Prompt shipment with tracking. we ship in CLEAN SECURE NEW boxes Fine in Fine dust jacket. First edition. Palgrave Macmillan hardcover
1982réf. BING595RM4361Cambridge University Press 1982-05-31. Hardcover. Like New. Prompt shipment with tracking. we ship in CLEAN SECURE NEW boxes First edition. Fine in fine dust jacket Cambridge University Press hardcover
1989réf. Q-0878916725Research & Education Association 1989-11-24. Paperback. New. In shrink wrap. Looks like an interesting title! Research & Education Association paperback